
Diversified Shares Fund
Australian and global equity markets were underpinned by strong corporate earnings and continued investment in artificial intelligence ("AI") over the three months to 30 September 2026, although market conditions became more volatile as interest rates and bond yields rose and geopolitical uncertainty persisted. Against this backdrop, the Diversified Shares Fund (Wholesale) (the “Fund”) returned-0.6%, compared with +1.3% for its benchmark, while maintaining adherence to Australian Ethical’s investment charter.
The Australian equity market was characterised by significant dispersion across sectors and individual companies. August reporting season saw strong gains in Healthcare and Materials, while Consumer Discretionary, Real Estate and Financials declined. This reversed in September, when the ASX 200 fell 2.4% as higher domestic and global bond yields weighed on valuations. Healthcare was the only sector to rise significantly, while Technology fell 7.3% as concerns about potential AI disruption to software companies resurfaced.
Interest rates became an increasingly important influence on markets. The Reserve Bank of Australia raised the cash rate by 25 basis points to 4.6% in September, while the Australian 10-year government bond yield ended the quarter at 5.35%. Higher yields placed pressure on rate-sensitive and longer-duration equities, with Utilities, Real Estate and other bond-proxy exposures particularly sensitive to rising rates. At the same time, AI remained an important source of earnings growth, particularly in global markets. Investors became increasingly focused on whether AI investment could translate into earnings and cash flows, contributing to a divergence between AI infrastructure companies and software businesses facing potential disruption.
Factor leadership also shifted significantly through the quarter. July saw an unwind in crowded Momentum positions associated with AI before conditions subsequently stabilised. By September, Australian Momentum and Growth were among the weakest styles, while US Momentum remained strong. These contrasting outcomes across markets, sectors and styles reinforced the benefits of maintaining diversified exposures rather than relying heavily on a single investment style.
For the Fund, relative performance reflected both its structural sector exposures and individual stock outcomes. The Fund's ethical investment universe results in underweights to Energy and Materials, which were two of the stronger performing sectors during the quarter, resulting in relative underperformance. The Fund maintains greater exposure to areas including Healthcare and Information Technology. CSL Limited, Microsoft Corporation and Northern Star Resources Ltd were the three largest contributors, while Commonwealth Bank of Australia, PLS Group Limited and Wesfarmers Limited were among the largest detractors.
Over the quarter, the Fund maintained an overweight position in Cleanaway Waste Management. Cleanaway helps enable Australia's circular economy by collecting, recycling and recovering materials that would otherwise be sent to landfill, reducing waste and supporting more efficient use of resources. The company operates one of Australia's largest waste management and resource recovery networks and is focused on improving recycling outcomes, reducing emissions and protecting the environment. During the year, the Fund benefited from a takeover proposal for Cleanaway from EQT Infrastructure at $3.13 per share (a 32% premium to the last closing share price), valuing the company at approximately $9.4 billion and reflecting the strategic value of Cleanaway's waste management infrastructure and resource recovery capabilities. The offer is still being considered by the Cleanaway Board and Management team.
Outlook
The outlook is broadly positive, but there is less room for things to go wrong. Corporate earnings and AI-related investment remain supportive, but higher interest rates, elevated bond yields and geopolitical uncertainty make it harder to justify current market valuations. September showed how quickly geopolitical events can push energy prices and inflation expectations higher. Further escalation in the Middle East could quickly weigh on investor confidence.
Within Australia, the combination of higher rates and softer domestic activity warrants some caution. August reporting season showed negative earnings revisions across much of the market, while the ASX 300 remained on an above-average valuation multiple at the end of September. Further company updates will therefore be important in determining whether earnings can support current valuations as tighter monetary policy flows through the economy.
At the same time, elevated dispersion across sectors, styles and individual companies should continue to create opportunities for a diversified investment approach.
Diversified Shares (Wholesale) Fund Performance
As at 30 September 2026*
| Fund | Benchmark^ | |
|---|---|---|
| 3 Months | -0.6% | 1.3% |
| 6 Months | 5.9% | 7.6% |
| 1 Year | -1.8% | 4.3% |
| 3 Years P.A. | 10.2% | 13.3% |
| 5 Years P.A. | 5.4% | 9.1% |
| 10 Years P.A. | 8.7% | 10.0% |
| Since Inception P.A. | 11.3% | 12.1% |
^75% S&P/ASX 300 Accumulation Index and 25% MSCI World ex Australia Index. Past performance is not a reliable indicator of future performance.
Inception date: 23/01/2012.
Diversified Shares (Retail) Fund Performance
As at 30 September 2026*
| Fund | Benchmark^ | |
|---|---|---|
| 3 Months | -0.7% | 1.3% |
| 6 Months | 5.7% | 7.6% |
| 1 Year | -2.3% | 4.3% |
| 3 Years P.A. | 9.8% | 13.3% |
| 5 Years P.A. | 4.9% | 9.1% |
| 10 Years P.A. | 7.9% | 10.0% |
| Since Inception P.A. | 8.1% | 8.6% |
^Benchmark is 75% S&P/ASX 300 Accumulation Index and 25% MSCI World ex Australia Index. Past performance is not a reliable indicator of future performance.
Inception date: 03/11/1997.
Contributors and detractors
Key contributors
+62.7%
CSL Limited (CSL-AU)
+37.1%
Microsoft Corporation (MSFT-US)
+32.4%
Northern Star Resources Ltd (NST-AU)
Key detractors
-6.7%
Commonwealth Bank of Australia (CBA-AU)
-22.4%
PLS Group Limited (PLS-AU)
-13.9%
Wesfarmers Limited (WES-AU)Contributors
-
CSL (CSL) outperformed strongly over the quarter, as investor confidence continued to build around the company's improving outlook and the recovery in its core plasma franchise. Growth has re-emerged in the plasma business, which remains the key driver of long-term value, while management's focus on operational execution, cost efficiencies and performance improvement is beginning to gain traction across the group. The market responded positively to signs of stabilisation under the interim CEO and increasing confidence that earnings momentum is strengthening. We believe CSL remains well positioned to deliver attractive earnings growth, supported by its leading global market position and the enduring structural growth in plasma demand.
-
Microsoft Corporation (MSFT-US) returned 37.1% in the September quarter, as its fiscal fourth-quarter result eased concerns about whether its heavy AI spending would pay off. Azure revenue grew 43%, ahead of guidance, and Microsoft 365 Copilot passed 30 million paid seats, up from 20 million in April.
-
Northern Star Resources Ltd (NST-AU) returned 32.4% in the September quarter, supported by a strong end to FY26 and a takeover approach from Gold Fields. June-quarter gold sales rose 14% to 433koz, and commissioning of the expanded KCGM mill began on schedule. Its August result delivered underlying net profit after tax (NPAT) of A$1.8 billion, up 26%, and a final dividend ahead of expectations, although FY27 cost guidance was higher than analysts had forecast. In late September, the board unanimously rejected an unsolicited proposal from Gold Fields worth A$27.00 per share, a 22% premium to the share price before the approach.
Detractors
-
Commonwealth Bank of Australia (CBA-AU) returned -6.7% in the September quarter, as its FY26 result did little to support its premium valuation. Cash profit rose 7% to A$10.98 billion, in line with expectations, and the small beat came mainly from lower loan impairments rather than stronger revenue. Investors focused instead on a 15% fall in home loan applications since the May Federal Budget and on rising competition for both mortgages and deposits.
-
PLS Group Limited (PLS-AU) returned -22.4% in the September quarter, despite record results. FY26 revenue rose 152% to A$1.9 billion, PLS returned to profit, and it declared its first dividend in two years, ahead of expectations. However, in September, Chinese lithium carbonate prices fell by about a quarter during the month amid doubts that battery demand could keep pace with strong cell production. Australian producers' guidance for higher FY27 output added to concerns about supply.
-
Wesfarmers Limited (WES-AU) returned -13.9% in the September quarter, despite a broadly resilient FY26 result. Early FY27 trading showed softer retail momentum, with sales growth across Bunnings, Kmart and Officeworks below market expectations. Weaker cash generation and a softer consumer and housing backdrop also weighed on the outlook.
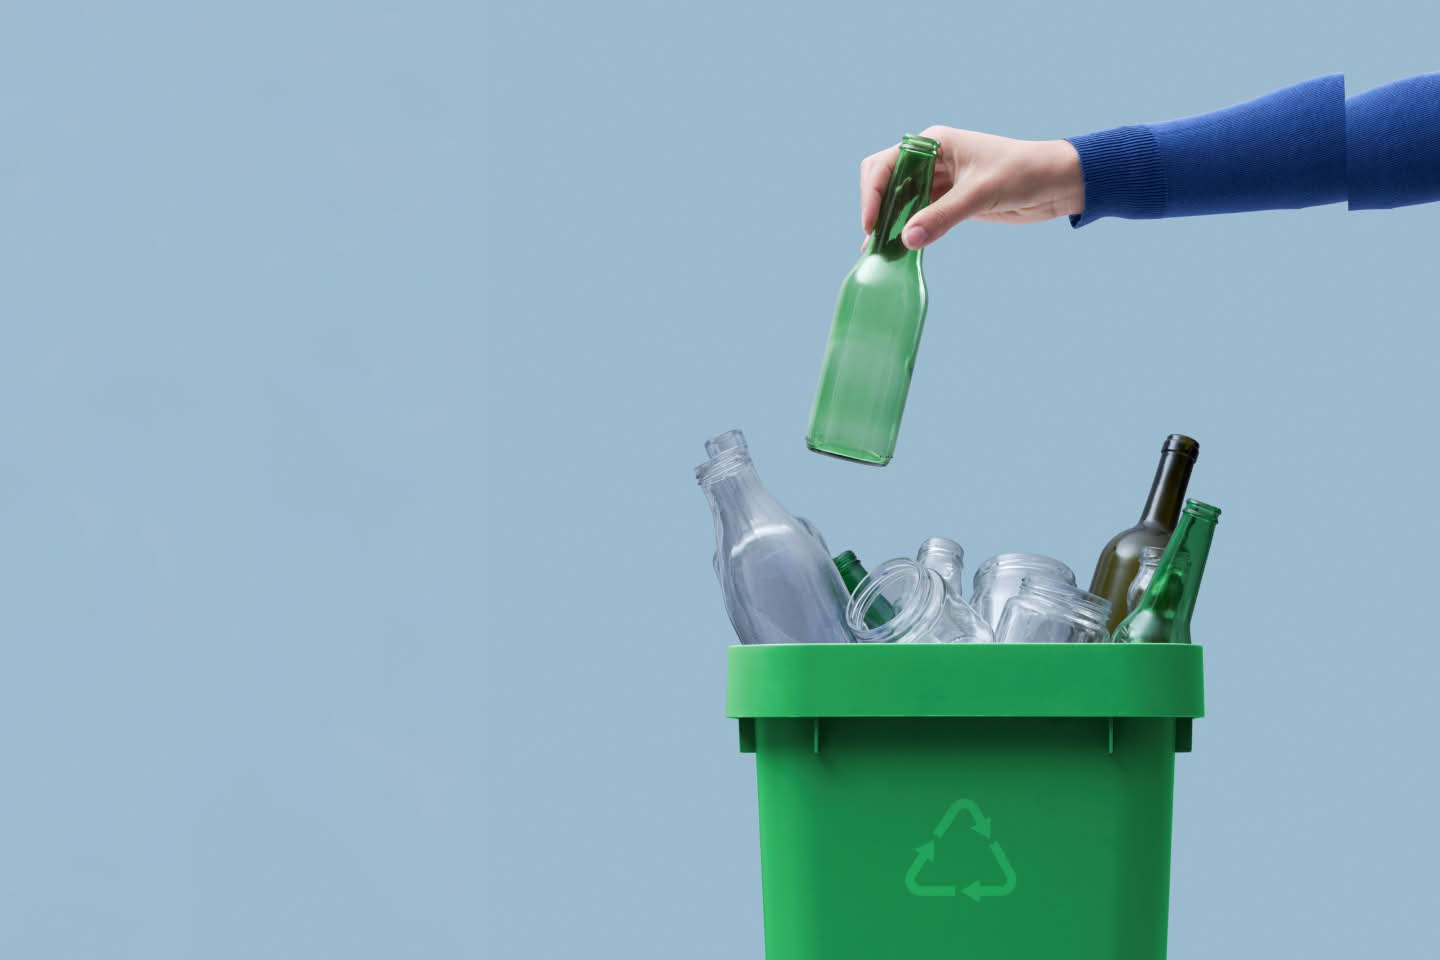
The Fund held an overweight position in Cleanaway Waste Management, a business helping build Australia's circular economy through waste collection, recycling and resource recovery. A takeover proposal during the year reflected the long-term strategic value of investing in sustainable waste infrastructure.
Portfolio changes
Additions to the Fund
-
NetScout Systems, Inc. (NTCT-US) – NetScout Systems, Inc. provides network observability, service assurance, cybersecurity and DDoS protection solutions to telecommunications carriers, enterprises and government agencies.
-
AIXTRON SE (AIXA-DE)) – AIXTRON SE develops and manufactures deposition equipment for the semiconductor industry. Its systems are used to produce compound semiconductor materials such as gallium nitride and silicon carbide, which are used in power electronics and optoelectronics.
-
Global Payments Inc. (GPN-US) – Global Payments, Inc. engages in the provision of payment technology and software solutions. It operates through the Merchant Solutions and Issuer Solutions segments. The Merchant Solutions segment offers payment technology and software solutions globally, primarily to small and medium-sized businesses, as well as select mid-market and enterprise customers.
All company additions recently received ethical approval and were added to the portfolio as part of the optimisation process, which aims to reduce tracking error.
Divestments
-
Atlas Arteria (ALX-AU) – Atlas Arteria was the subject of a hostile takeover by IFM Investors during the quarter. After initially rejecting the offer as undervaluing the company, Atlas Arteria remained listed when IFM's $5.10 per security offer closed in July. IFM secured a controlling stake of approximately 67%, but did not acquire the remaining minority interests. We sold our position into the offer. Post the close of the offer, the share price remains materially under $5.10.
-
Qube Holdings Ltd. (QUB-AU) – Qube Holdings Ltd. is a provider of ports and terminal infrastructure and supply chain services across Australia, New Zealand and South-East Asia. Qube was acquired by a Macquarie Asset Management-led consortium, at A$5.20 cash per share, less dividends paid during the quarter.
-
Schroders PLC (SDR-GB) – Schroders Plc is an asset management company, which engages in investment management activities. The holding was sold ahead of the completion of its acquisition by Nuveen on 1 October 2026.
The Fund maintains greater exposure to areas including Healthcare and Information Technology, with CSL Limited, Microsoft Corporation and Northern Star Resources among the largest contributors.
Corporate earnings and AI-related investment remain supportive, but higher interest rates, elevated bond yields and geopolitical uncertainty make it harder to justify current market valuations.
Sector allocation
Sector overweights
Communication Services, Financials, Health Care, Industrials, Information Technology, Real Estate, Utilities
Sector underweights
Consumer Discretionary, Consumer Staples, Energy, Materials
Interests in Australian Ethical Managed Funds are issued by Australian Ethical Investment Ltd (ABN 47 003 188 930, AFSL 229949) the Responsible Entity of the Australian Ethical Managed Funds.
The information is of a general nature and is not intended to provide you with financial advice or take into account your personal objectives, financial situation or needs. Before acting on the information, consider its appropriateness to your circumstances and read the Financial Services Guide, relevant product disclosure statement (PDS) and Target Market Determination (TMD) available on our website. You may wish to seek financial advice from a licensed financial adviser before making an investment decision. Past performance is not a reliable indicator of future performance.
Investing ethically and sustainably means that the investment universe will generally be more limited than non-ethical, non-sustainable portfolios in similar asset classes. This means that the portfolio(s) may not have exposure to specific assets which over or underperform over the investment cycle, and so the returns and volatility of the portfolio(s) may be higher or lower than non-ethical, non-sustainable portfolios over all investment time frames.
Our investment restrictions include thresholds and other tolerances that vary depending on the investment. We apply both qualitative and quantitative analysis when making investment decisions and may invest where we believe the positive aspects outweigh the negative. From time to time, we may use derivatives that provide temporary exposure to a broad market index, such as the S&P/ASX 200. This does not involve direct investment in, or ownership of, the underlying companies. For more information, please read our Ethical Guide.
*Total returns are calculated using the sell (exit) price, net of management fees and gross of tax as if distributions of income have been reinvested at the actual distribution reinvestment price. The actual returns received by an investor will depend on the timing, buy and exit prices of individual transactions. Return of capital and the performance of your investment in the fund are not guaranteed. Past performance is not a reliable indicator of future performance. Figures showing a period of less than one year have not been adjusted to show an annual total return. Figures for periods of greater than one year are on a per annum compound basis. The current benchmark may not have been the benchmark over all periods shown in the above chart and tables. The calculation of the benchmark performance links the performance of previous benchmarks and the current benchmark over the relevant time periods.
This commentary may contain material provided by third parties derived from sources believed to be accurate at its issue date. While such material is published with necessary permission, Australian Ethical accepts no responsibility for the accuracy or completeness of, nor does it endorse any such third party material. To the maximum extent permitted by law, we intend by this notice to exclude liability for this third-party material.
The information contained in this document is believed to be accurate at the time of compilation.