
High Conviction Fund
The High Conviction Fund (the ‘Fund’) declined marginally over the September quarter, returning -0.5% net of fees for the three months, whilst the ASX300 index returned 1.3%. The short-term effects of geopolitical conflict and persistent inflationary pressures driving interest rates higher provided a near-term drag on the portfolio, given the tilt towards long duration, quality growth companies. Despite this, the portfolio performed strongly through the annual results season in August, highlighting the positive returns from our fundamental investment process that identifies undervalued quality businesses.
The Healthcare sector was the strongest contributor to portfolio returns in the quarter, with the portfolio’s holdings in Resmed, Fisher & Paykel Healthcare, and CSL all performing well. CSL rebounded strongly, with the business stabilising under a temporary CEO, operating efficiencies being successfully pursued, and growth returning to its key plasma business. We believed the market had become overly pessimistic regarding the company's earnings outlook, providing an opportunity for patient investors with a longer investment time horizon. With a new CEO to be appointed soon, we think there remains opportunity for ongoing share price appreciation. The portfolio also benefited from the emergence of corporate activity, with Reliance Worldwide and Cleanaway receiving takeover approaches during the quarter. We view this heightened level of strategic interest as further evidence that a number of high-quality industrial companies continue to trade below their intrinsic value.
Offsetting the strong gains made in the Healthcare and Industrials sectors was weakness in the Information Technology sector. Higher bond yields and the re-emergence of concerns relating to AI disruption combined to put downward pressure on software and platform technology stocks over the quarter. Xero, SiteMinder, and CAR Group were all weaker, despite earnings updates released in August showing that underlying fundamentals remain strong. With valuations becoming increasingly attractive, we continue to invest in these names. Our research process continues to identify the technology companies we hold to be beneficiaries of AI.
Our underweight to the Materials and Energy sectors, was a modest headwind. This positioning reflects our Ethical Charter, which prioritises companies aligned with the transition to a lower-carbon economy.
During the quarter, we added Capstone Copper, Sims Limited and Netwealth to the portfolio. Sims is a strong example of how the circular economy can cut emissions at industrial scale. One of the world's largest metal recyclers, Sims supplies recycled steel, copper and aluminium to manufacturers, and its scrap is the key input for electric arc furnaces, which make steel with far lower emissions than coal-based blast furnaces. In FY26, Sims recycled 5.9 million tonnes of steel scrap, avoiding an estimated 9.6 million tonnes of CO₂e, more than 130 times the emissions from its own operations. Its Sims Lifecycle Services business also extends the life of data centre hardware, repurposing 16.8 million servers and memory units during the year and avoiding around 479,000 tonnes of CO₂e. The Fund re-entered Sims at an attractive valuation after the post-result sell-off. FY26 underlying EBIT rose 168% to $468m, ahead of guidance, as US tariffs and growing electric arc furnace demand lifted the metals businesses, while Lifecycle Services adds growing exposure to data centre recycling, with GPU repurposing the next opportunity. With a sound balance sheet, strong free cash flow and a share price of around 12–13x forecast earnings, Sims shows how our investment capital can support decarbonisation while delivering attractive returns.
The near-term macro backdrop is likely to create ongoing volatility on equity markets, which we think works to our advantage given our research driven, valuation-oriented investment process. The portfolio’s exposure to longer duration, quality growth companies positions it well to deliver superior returns over the long-term.
High Conviction (Wholesale) Fund Performance (with performance fee)
As at 30 September 2026*
| Fund | Benchmark^ | |
|---|---|---|
| 3 Months | -0.5% | 1.3% |
| 6 Months | 4.6% | 5.5% |
| 1 Year | -9.6% | 2.4% |
| 3 Years P.A. | 4.5% | 11.3% |
| 5 Years P.A. | 1.7% | 7.5% |
| 10 Years P.A. | - | - |
| Since Inception P.A. | 1.7% | 7.5% |
^Benchmark is the S&P/ASX 300 Accumulation Index. Past performance is not a reliable indicator of future performance.
Inception date: 01/10/2021.
Contributors and detractors
Top 3 contributors to Fund return
+62.7%
CSL Limited (CSL)
+21.2%
Reliance Worldwide (RWC)
+11.1%
ResMed (RMD)
Top 3 detractors from Fund return
-35.0%
PEXA Group (PXA)
-33.1%
SiteMinder (SDR)
-21.2%
Xero (XRO)Contributors
-
CSL (CSL) outperformed strongly over the quarter, as investor confidence continued to build around the company's improving outlook and the recovery in its core plasma franchise. Growth has re-emerged in the plasma business, which remains the key driver of long-term value, while management's focus on operational execution, cost efficiencies and performance improvement is beginning to gain traction across the group. The market responded positively to signs of stabilisation under the interim CEO and increasing confidence that earnings momentum is strengthening. We believe CSL remains well positioned to deliver attractive earnings growth, supported by its leading global market position and the enduring structural growth in plasma demand.
-
Reliance Worldwide (RWC) was a strong contributor over the quarter following a takeover proposal, which highlighted the strategic value of the business and drove a significant re-rating in the share price. Towards the end of the quarter, the Fund trimmed some of its position as the share price moved above the merger-arbitrage value and began to reflect market expectations of a potential competing bid. We continue to see value in the underlying business, supported by its market-leading brands, strong cash generation and leverage to a recovery in US housing activity.
-
ResMed (RMD) was a strong contributor over the quarter as the company continued to execute well across both its device and mask businesses. Growing awareness of sleep apnoea, resilient demand and ongoing gross margin initiatives supported earnings growth, while the balance sheet remains a source of strength through capital returns and investment in future growth opportunities. We remain optimistic on the outlook for ResMed.
Detractors
-
PEXA (PXA) underperformed over the quarter, with the share price coming under pressure as uncertainty around the future pricing framework for the Australian exchange business weighed on investor sentiment. While the FY27 outlook factors in softer Australian property transfer volumes, investor concern is primarily driven by uncertainty around the final outcome of the IPART pricing review and its potential implications for the Australian exchange business. Despite this regulatory overhang, the core exchange platform remains a critical part of the property settlement ecosystem. We continue to see value in the business beyond the current regulatory overhang, with the UK operation providing a source of longer-term growth that we believe is not reflected in the current share price.
-
SiteMinder (SDR) detracted over the quarter, with the share price coming under pressure following its FY26 result as investors reassessed the company's medium-term growth outlook, while concerns around the potential impact of AI developments on the travel technology sector also weighed on sentiment. The result included a reduction in annual recurring revenue growth expectations from the previous 30% target to growth in the 20s for FY27. Despite this, underlying operating metrics remained sound, including stable churn and strong customer economics. We continue to see value in the business beyond the current uncertainty, with ongoing adoption of Smart Platform products expected to support future growth over time.
-
Xero (XRO) underperformed over the quarter, as renewed concerns around AI-driven disruption and a US competitor downgrade weighed on sentiment. While these concerns impacted the share price, we continue to see evidence of a durable competitive advantage through Xero's strong customer retention, ecosystem expansion and attractive positioning within the small business software market. With the stock trading at historical low multiples, we remain constructive on Xero's long-term positioning, supported by its competitive advantages and significant growth opportunity in the US market.
We added Capstone Copper as a high-conviction copper exposure, with the valuation not fully reflecting its organic growth pipeline, improving cost profile and leverage to long-term copper demand.
Portfolio changes
Additions to the Fund
- Capstone Copper Corp. (CSC) – We added Capstone Copper as a high-conviction copper exposure, with the valuation not fully reflecting its organic growth pipeline, improving cost profile and leverage to long-term copper demand.
- Netwealth Group Ltd. (NWL) – We added a position in Netwealth, on the back of recent share price weakness. With the stock trading at an historical low multiple, the current price underappreciates the company's strong market-share growth, scalable platform economics and long-term earnings potential.
- Sims Ltd. (SGM) – We added Capstone Copper as a high-conviction copper exposure, with the valuation not fully reflecting its organic growth pipeline, improving cost profile and leverage to long-term copper demand.
Divestments from the Fund
-
IPH Ltd. (IPH) – We reduced our holding in IPH during the quarter, recognising management's turnaround strategy but acknowledging that the pathway to improved performance is likely to be gradual.
-
Nuix Ltd. (NXL) – We exited a relatively small position in Nuix in the Fund to reallocate capital to other opportunities.
-
Qube Holdings Ltd. (QUB) – We exited Qube following completion of the takeover by the Macquarie-led consortium, crystallising strong returns and redeploying capital into opportunities with greater upside potential.
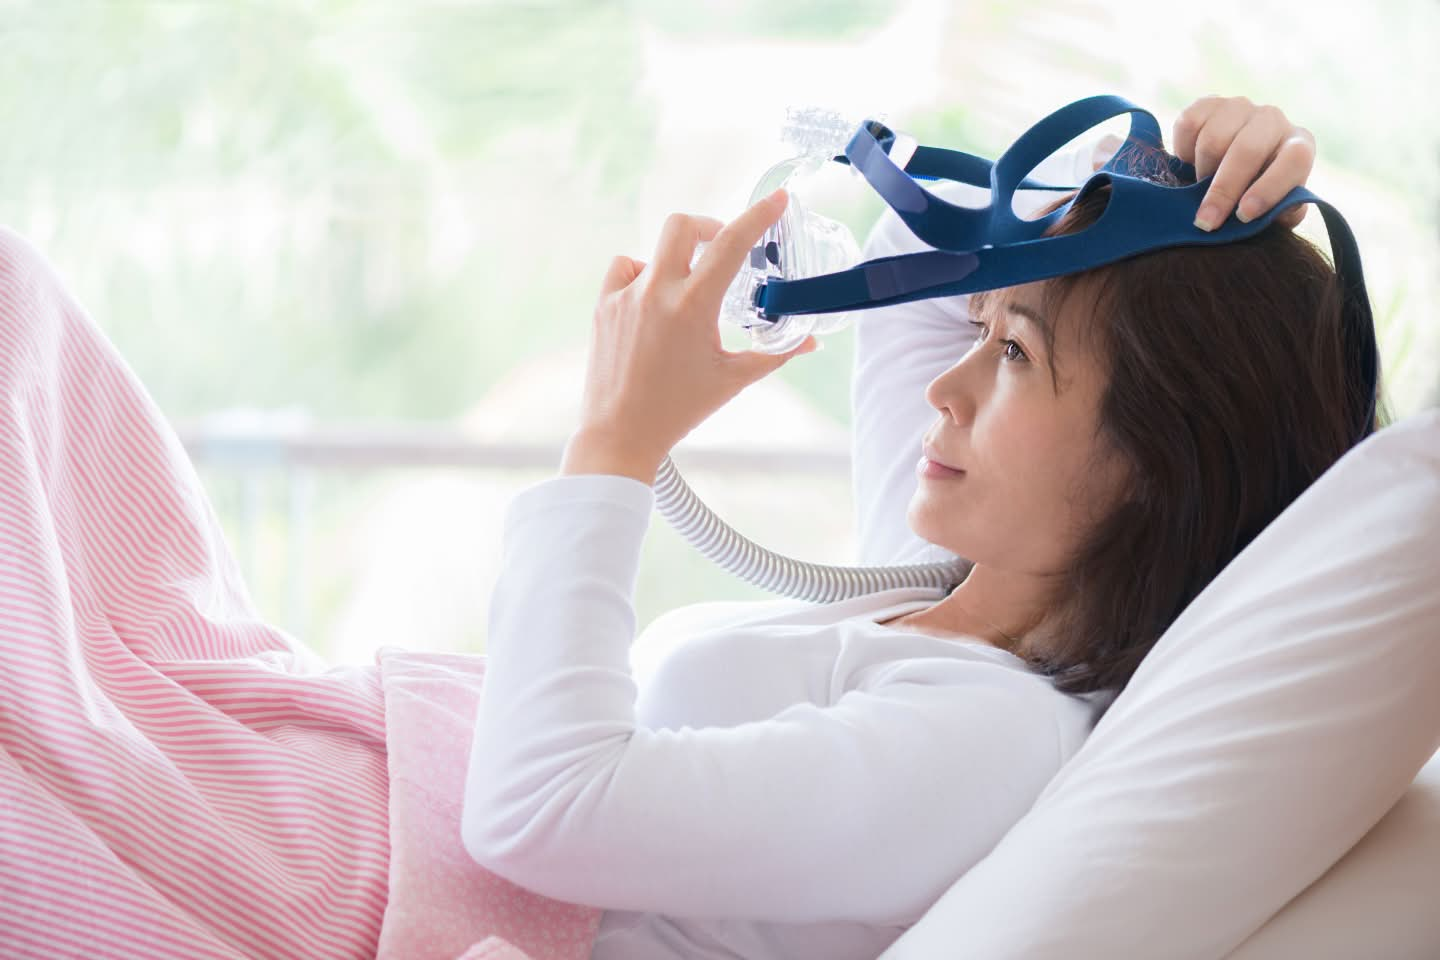
ResMed was a strong contributor over the quarter as the company continued to execute well across both its device and mask businesses.
Sector allocation
Sector overweights
Communication Services, Health Care, Information Technology, Real Estate, Utilities
Sector underweights
Consumer Discretionary, Consumer Staples, Energy, Financials, Industrials Materials
The Healthcare sector was the strongest contributor to portfolio returns in the quarter, with the portfolio’s holdings in Resmed, Fisher & Paykel Healthcare, and CSL all performing well.
Interests in Australian Ethical Managed Funds are issued by Australian Ethical Investment Ltd (ABN 47 003 188 930, AFSL 229949) the Responsible Entity of the Australian Ethical Managed Funds.
The information is of a general nature and is not intended to provide you with financial advice or take into account your personal objectives, financial situation or needs. Before acting on the information, consider its appropriateness to your circumstances and read the Financial Services Guide, relevant product disclosure statement (PDS) and Target Market Determination (TMD) available on our website. You may wish to seek financial advice from an authorised tax or financial adviser before making an investment decision. Past performance is not a reliable indicator of future performance.
Investing ethically and sustainably means that the investment universe will generally be more limited than non-ethical, non-sustainable portfolios in similar asset classes. This means that the portfolio(s) may not have exposure to specific assets which over or underperform over the investment cycle, and so the returns and volatility of the portfolio(s) may be higher or lower than non-ethical, non-sustainable portfolios over all investment time frames.
Our investment restrictions include thresholds and other tolerances that vary depending on the investment. We apply both qualitative and quantitative analysis when making investment decisions and may invest where we believe the positive aspects outweigh the negative. From time to time, we may use derivatives that provide temporary exposure to a broad market index, such as the S&P/ASX 200. This does not involve direct investment in, or ownership of, the underlying companies. For more information, please read our Ethical Guide.
*Total returns are calculated using the sell (exit) price, net of management fees and gross of tax as if distributions of income have been reinvested at the actual distribution reinvestment price. The actual returns received by an investor will depend on the timing, buy and exit prices of individual transactions. Return of capital and the performance of your investment in the fund are not guaranteed. Past performance is not a reliable indicator of future performance. Figures showing a period of less than one year have not been adjusted to show an annual total return. Figures for periods of greater than one year are on a per annum compound basis. The current benchmark may not have been the benchmark over all periods shown in the above chart and tables. The calculation of the benchmark performance links the performance of previous benchmarks and the current benchmark over the relevant time periods.
This commentary may contain material provided by third parties derived from sources believed to be accurate at its issue date. While such material is published with necessary permission, Australian Ethical accepts no responsibility for the accuracy or completeness of, nor does it endorse any such third party material. To the maximum extent permitted by law, we intend by this notice to exclude liability for this third-party material.
The information contained in this document is believed to be accurate at the time of compilation.