
Multi-Asset Funds
The Balanced and High Growth Funds generated positive returns over the quarter. The Moderate Fund was broadly flat, while the Conservative Fund recorded a small negative return. These absolute returns were supported by strong performance from International Equities, with Artificial Intelligence continuing to dictate market movements. Weakness in Fixed Income markets detracted from returns with a re-escalation of tensions in the Middle East, a return of inflation fears, and central bank monetary policy turning restrictive. Relative performance was slightly below benchmark across most Funds, primarily due to underweights to Energy and Materials within domestic equities, which were two of the stronger performing sectors during the quarter. The Conservative Fund performed broadly in line with its benchmark.
The Funds’ allocations to private market assets, such as private equity and unlisted infrastructure also added to return. One such example, via one of our investment partners, is an allocation to HealthifyMe, India & Southeast Asia's largest digital wellness platform. Serving more than 40 million users, the company combines AI-enabled technology with personalised nutrition and fitness coaching to improve health outcomes at scale. In doing so, the company is helping to tackle the growing burden of obesity and lifestyle-related diseases by making preventative healthcare more affordable and accessible.
Private credit was also a positive contributor to returns over the quarter (and the year), though recent media attention on parts of the private credit sector has understandably prompted questions from investors. Importantly, it is worth noting that the Funds' exposure to private credit is minimal, representing approximately 1% of portfolio assets, and is focused on purpose-driven areas that differ materially from the segments that have attracted recent scrutiny. Rather than lending to commercial real estate projects or highly leveraged corporate borrowers, our exposure is largely spread across renewable energy infrastructure debt, asset-backed lending secured by diversified pools of residential mortgages, social loan notes and microfinance institutions. These investments are generally supported by tangible assets, contractual cashflows or government-linked support, and align with Australian Ethical's objective of delivering competitive returns while creating positive environmental and social impact. As a result, we believe the Funds are well positioned to benefit from the diversification offered by private lending without taking on the types of risks that have been the focus of recent market concerns.
Outlook and opportunities
The outlook for Multi-Asset portfolios is broadly positive, but two-sided. Global growth remains supported by resilient corporate earnings, AI infrastructure investment and expanding technology adoption. However the benefits are concentrated and high real rates, elevated energy costs and weaker lower-income consumption are making it harder for the broader market to perform. Fixed income is becoming relatively more attractive after the rise in yields. Markets appear to expect further interest rate rises, while policy lags, mortgage sensitivity and slowing money growth may ultimately weaken economic activity. This supports gradually adding duration.
We continue to seek renewable energy and electrification investments as we believe they offer a resilient way to gain exposure to the AI thematic. Data centre growth is increasing demand for reliable electricity, reinforcing the investment required in generation, grids, storage and related infrastructure. Importantly, this opportunity is not dependent on AI alone. The transition toward net zero by 2050 will also require substantial electrification across transport, buildings and industry. Electrification investments therefore benefit from multiple long-term demand drivers and may provide a more diversified and durable expression of AI growth than direct exposure to technology companies.
Overall, the portfolios remain diversified and moderately pro-risk.
Multi-Asset Funds (Wholesale): Performance vs benchmark*
| Since inception (% P.A.) | 5 years (% P.A.) | 3 years (% P.A.) | 1 year (%) | 3 months (%) | |
|---|---|---|---|---|---|
| Balanced (Wholesale) | 7.4 | 5.0 | 9.1 | 3.6 | 0.4 |
| Benchmark^ | 7.7 | 6.6 | 10.2 | 5.4 | 0.5 |
| Alpha | -0.3 | -1.7 | -1.0 | -1.9 | -0.1 |
| High Growth (Wholesale) | 11.1 | 6.4 | 11.3 | 4.0 | 0.7 |
| Benchmark^ | 11.1 | 9.0 | 13.1 | 6.6 | 1.0 |
| Alpha | 0.0 | -2.6 | -1.8 | -2.6 | -0.2 |
| Moderate (Wholesale) | 9.2 | - | - | 3.3 | -0.0 |
| Benchmark^ | 9.3 | - | - | 4.3 | 0.1 |
| Alpha | -0.1 | - | - | -1.0 | -0.1 |
| Conservative (Wholesale) | 6.2 | - | - | 3.4 | -0.4 |
| Benchmark^ | 5.8 | - | - | 3.3 | -0.4 |
| Alpha | 0.4 | - | - | 0.1 | 0.0 |
*All returns are net of fees for the Wholesale option. Find more information on these funds via the managed funds page including Retail performance. Past performance is not a reliable indicator of future performance.
^ Benchmark: SAA Weighted Index.
Balanced Fund SAA Weighted Benchmark changed from Morningstar Multi-sector Balanced to SAA Weighted Benchmark from 1 Sep 2012. The historical benchmark returns are calculated by linking indices.
High Growth SAA Weighted Benchmark changed from 75% S&P/ASX 200/25% MSCI World ex Australia to SAA Weighted Benchmark from 1 October 2021. Previously, benchmark changed from S&P ASX 200 to 75% S&P/ASX 200 Industrials/25% MSCI Global Climate from 29 August 2013, then to 75% S&P/ASX 200 Industrials/25% MSCI World ex Australia from 1 July 2016, then to 75% S&P/ASX 200/25% MSCI World ex Australia from 13 August 2019. The historical benchmark returns are calculated by linking indices.
Contributors and detractors
Top 3 asset classes
+2.0%
International Equity
+7.2%
Growth Alternatives
+2.7%
Defensive Alternatives
Bottom 3 asset classes
-3.2%
Globall Fixed Income
-2.2%
Property
-1.6%
Domestic Fixed IncomeContributors
- International Equity – The Information Technology and Financials sector provided the bulk of absolute returns, with software companies like Atlassian (+130%) and Workday (+54%) staging a long-awaited comeback following strong results, and Asian banks and insurers, such as OCBC (+32%) and Daiichi Life (+10%), benefiting from a rising interest rate environment and strong earnings results.
- Growth Alternatives – Domestic companies assisting in the rollout of Artificial Intelligence were key drivers of performance within the asset class, such as electrical engineering and contracting firms.
- Defensive Alternatives – Insurance-linked securities continued to perform well thanks to subdued loss activity over the quarter, as well as stable interest income from debt investments in microfinance institutions and renewable energy infrastructure projects
Detractors
- Global Fixed Income – Bond yields across the globe (with the exception of China) rose as fears of inflation began to resurface given higher energy prices, supply-chain disruptions and resilient economic activity raised the prospect that inflation may remain above central bank targets for longer than previously expected. This resulted in many central banks hiking interest rates, having paused their easing cycle at the start of the calendar year.
- Property – Returns in the asset class were negatively impacted by our listed property allocation, with the underlying global listed property benchmark declining -6% over the quarter. Weakness was broad-based as higher bond yields and interest rate expectations weighed on valuations.
- Domestic Fixed Income – In tandem with global fixed income markets, Australian bond yields rose as the Reserve Bank of Australia hiked interest rates for the fourth time this year, bringing the overnight cash rate to a 15-year high of 4.6%.
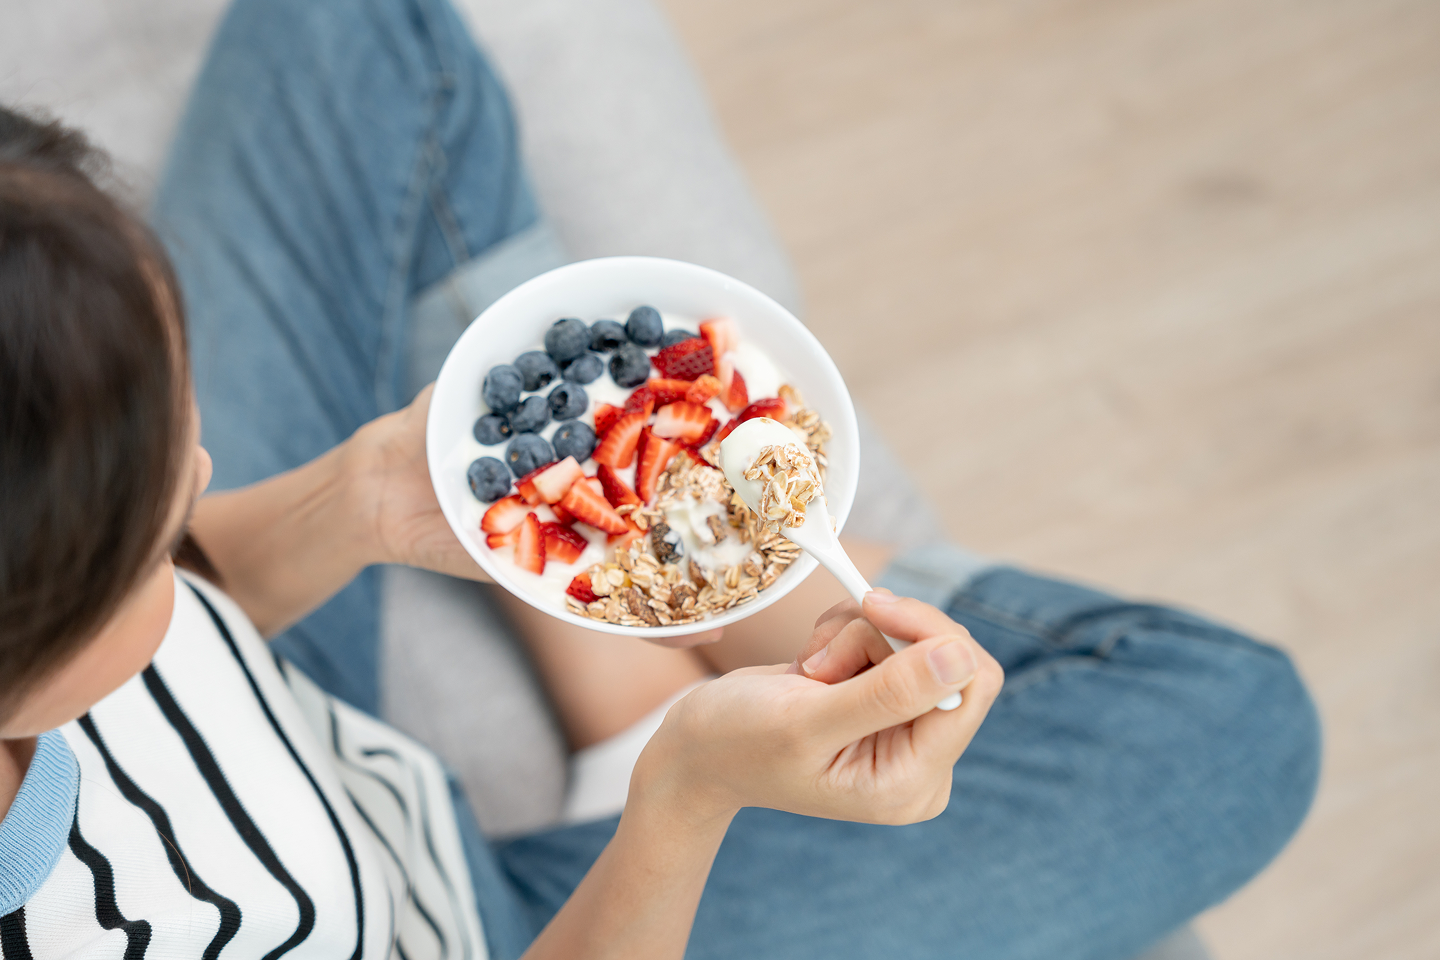
HealthifyMe, India & Southeast Asia's largest digital wellness platform, an investment in our private markets portfolio, combines AI-enabled technology with personalised nutrition and fitness coaching to improve health outcomes at scale.
Portfolio changes
Additions to the Funds
-
Japanese Yen – The Fund initiated a 0.5% position in the Japanese yen during the quarter. We believe the yen remains undervalued relative to long-term fundamentals and provides attractive diversification benefits within the portfolio. However, given the position incurs a cost over time, implementation was undertaken opportunistically at attractive entry levels. Following a period of yen appreciation, driven in part by increased expectations for Bank of Japan policy normalisation, the Fund realised profits on half of the position.
-
Ellerston 2050 Fund – Seeded by the Clean Energy Finance Corporation, the fund invests in a portfolio of Australian small to mid-sized companies helping drive the transition to a net-zero economy by 2050. The strategy focuses on emerging “enabler” businesses across areas such as electrification and clean technology, offering exposure to both structural decarbonisation themes and long-term growth opportunities.
Reductions from the Funds
-
Domestic Equities – The Fund reduced its allocation to Australian equities during the quarter. While the domestic market continues to benefit from a supportive economic backdrop, elevated valuations have reduced the equity risk premium and made prospective returns less compelling. In addition, the Australian market offers limited participation in the artificial intelligence-led growth opportunity that is increasingly shaping global equity markets.
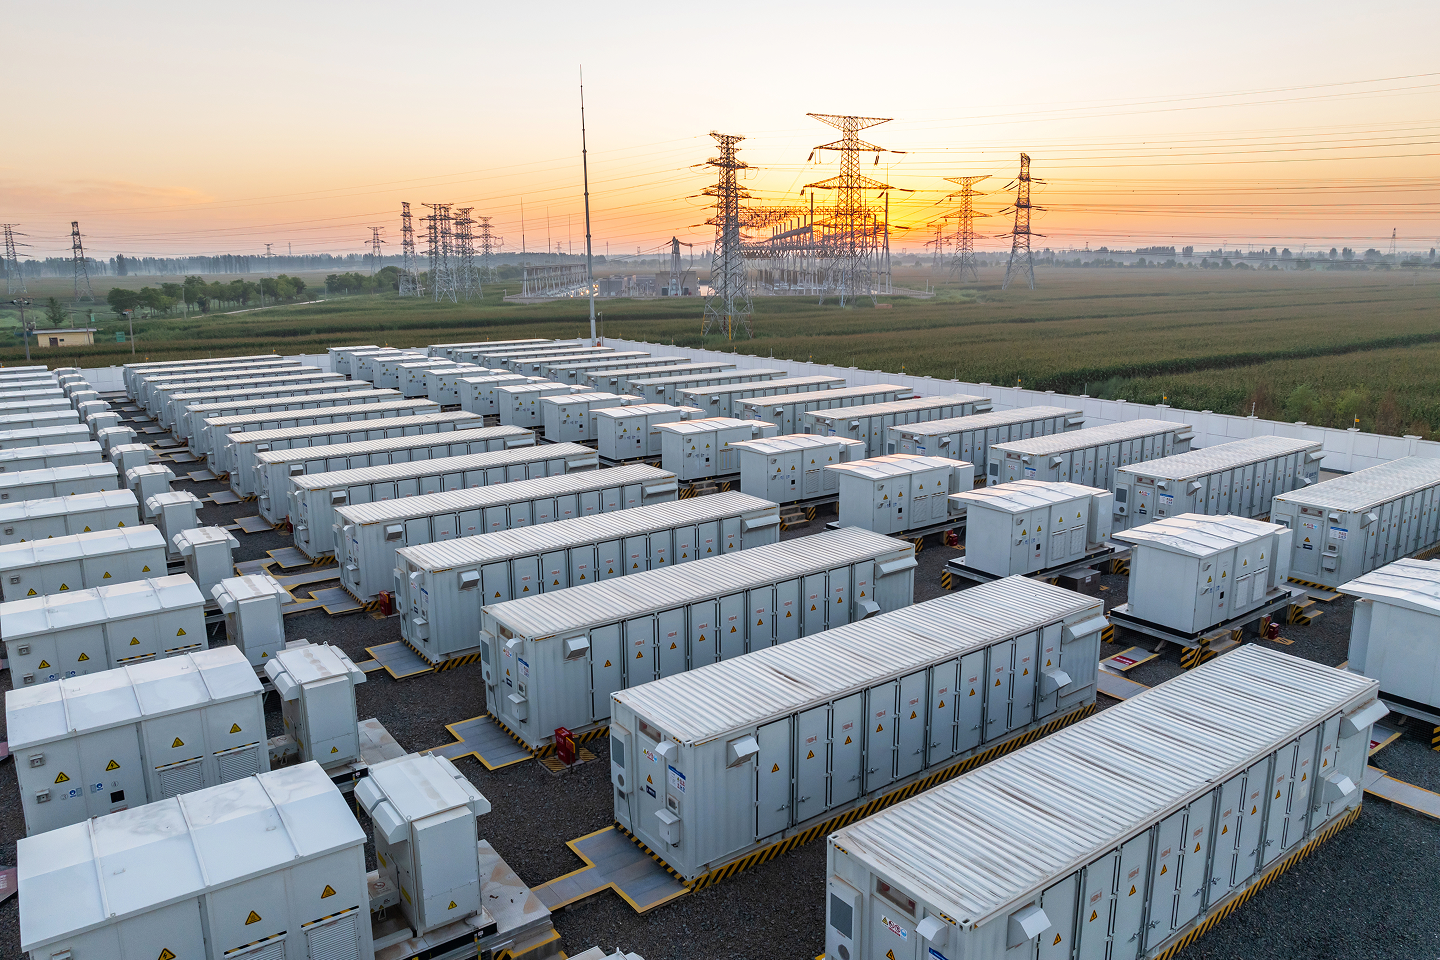
We continue to seek renewable energy and electrification investments as we believe they offer a resilient way to gain exposure to the AI thematic.
Electrification investments ... benefit from multiple long-term demand drivers and may provide a more diversified and durable expression of AI growth than direct exposure to technology companies.
Interests in Australian Ethical Managed Funds are issued by Australian Ethical Investment Ltd (ABN 47 003 188 930, AFSL 229949) the Responsible Entity of the Australian Ethical Managed Funds.
The information is of a general nature and is not intended to provide you with financial advice or take into account your personal objectives, financial situation or needs. Before acting on the information, consider its appropriateness to your circumstances and read the Financial Services Guide, relevant product disclosure statement (PDS) and Target Market Determination (TMD) available on our website.
You may wish to seek financial advice from an authorised tax or financial adviser before making an investment decision. Past performance is not a reliable indicator of future performance.
Investing ethically and sustainably means that the investment universe will generally be more limited than non-ethical, non-sustainable portfolios in similar asset classes. This means that the portfolio(s) may not have exposure to specific assets which over or underperform over the investment cycle, and so the returns and volatility of the portfolio(s) may be higher or lower than non-ethical, non-sustainable portfolios over all investment time frames.
Our investment restrictions include thresholds and other tolerances that vary depending on the investment. We apply both qualitative and quantitative analysis when making investment decisions and may invest where we believe the positive aspects outweigh the negative. From time to time, we may use derivatives that provide temporary exposure to a broad market index, such as the S&P/ASX 200. This does not involve direct investment in, or ownership of, the underlying companies. For more information, please read our Ethical Guide.
*Total returns are calculated using the sell (exit) price, net of management fees and gross of tax as if distributions of income have been reinvested at the actual distribution reinvestment price. The actual returns received by an investor will depend on the timing, buy and exit prices of individual transactions. Return of capital and the performance of your investment in the fund are not guaranteed. Past performance is not a reliable indicator of future performance. Figures showing a period of less than one year have not been adjusted to show an annual total return. Figures for periods of greater than one year are on a per annum compound basis. The current benchmark may not have been the benchmark over all periods shown in the above chart and tables. The calculation of the benchmark performance links the performance of previous benchmarks and the current benchmark over the relevant time periods.
This commentary may contain material provided by third parties derived from sources believed to be accurate at its issue date. While such material is published with necessary permission, Australian Ethical accepts no responsibility for the accuracy or completeness of, nor does it endorse any such third party material. To the maximum extent permitted by law, we intend by this notice to exclude liability for this third party material.
The information contained in this document is believed to be accurate at the time of compilation.