
Emerging Companies Fund
The Emerging Companies fund outperformed its ASX Small Industrials benchmark (-1.7%, net of fees vs the benchmark -4%) over the quarter. Relative performance was driven predominately through favourable individual stock selection, largely influenced by reporting season results announced in August. Over 70% of company results across the portfolio, based on our assessment, met or beat expectations through reporting season, and investors were rewarded with better relative share prices.
Overweight positions in some higher performing Financials stocks (Pepper Money and Cuscal Limited), and Consumer Staples stock, Graincorp) contributed to relative outperformance following better than expected results and better rural conditions.
An underweight position in Real Estate Investment Trusts (REITS) also contributed to relative performance. Selective defence related stocks (not owned) and mining services contractors (not owned) continue to rally and remain a headwind for the relative performance for the fund. Corporate activity, however, emerged with takeover offers tabled for OFX Limited, Reliance Limited and EQT Holdings during the quarter. Encouragingly, private equity and industry players are seeing long-term value in some of our companies. All three deals are yet to complete but positive sentiment driven by the offers have led to strong performance contribution during the period.
Macroeconomic and geopolitical developments remain challenging for sentiment towards smaller companies. Small caps are generally more favoured during periods of falling interest rates and rising risk appetite but increasing oil prices and ongoing geopolitical uncertainty is contributing to inflationary pressures, leading several central banks to keep rates elevated. Higher interest rates also continue to weigh on consumer confidence and economic activity. The fund remains underweight in REITS and consumer discretionary stocks, although we are starting to consider some opportunities as earnings are downgraded and valuations become more favourable across rate sensitive sectors.
The fund’s largest holdings span a wide range of sectors, including travel, medical research, telecommunications, payments, lending, utilities, infrastructure and technology. Each bring its own growth drivers, with many competing in niche markets against established players.
Urbanise.com Limited is one example. The company is sub $50 million market cap and sells software services to strata-lot managers to take care of trust accounting, compliance, maintenance and payments. Strata software companies need a bank integration so that money on deposit can move freely. These accounts often pay little to no interest and total an estimated $10-15bn funds held on deposit, representing an opportunity for Urbanise, in partnership with National Australia Bank, to gain share from incumbent banks such as Macquarie. National Australia Bank owns 15% of the company and has an option to buy a further 5% at a significant premium to the current share price. National Australia Bank and Urbanise are currently piloting their competing solution that offers a cloud-based solution, upgraded tech, more services and competitive pricing. We believe the opportunity for market share gains is substantial.
We remain cautious on the near-term outlook for domestic equities, whilst we continue to find compelling opportunities at the individual company level. Our disciplined focus on business quality, management capability and long-term fundamentals helps steer the fund, and position our investors in companies at attractive valuations that align strongly with our Ethical Charter.
One company we added to the portfolio during the quarter is Sims Limited, a business providing a strong example of how the circular economy can cut emissions at industrial scale. One of the world's largest metal recyclers, Sims supplies recycled steel, copper and aluminium to manufacturers, and its scrap is the key input for electric arc furnaces, which make steel with far lower emissions than coal-based blast furnaces. In FY26, Sims recycled 5.9 million tonnes of steel scrap, avoiding an estimated 9.6 million tonnes of CO₂e, more than 130 times the emissions from its own operations. Its Sims Lifecycle Services business also extends the life of data centre hardware, repurposing 16.8 million servers and memory units during the year and avoiding around 479,000 tonnes of CO₂e. The Fund re-entered Sims at an attractive valuation after the post-result sell-off. FY26 underlying EBIT rose 168% to $468m, ahead of guidance, as US tariffs and growing electric arc furnace demand lifted the metals businesses, while Lifecycle Services adds growing exposure to data centre recycling, with GPU repurposing the next opportunity. With a sound balance sheet, strong free cash flow and a share price of around 12–13x forecast earnings, Sims shows how our investment capital can support decarbonisation while delivering attractive returns.
Emerging Companies (Wholesale) Fund Performance
As at 30 September 2026*
| Fund | Benchmark^ | |
|---|---|---|
| 3 Months | -1.6% | -4.0% |
| 6 Months | -4.2% | 4.1% |
| 1 Year | -25.3% | -14.4% |
| 3 Years P.A. | 1.0% | 6.0% |
| 5 Years P.A. | -4.4% | -1.3% |
| 10 Years P.A. | 7.5% | 4.1% |
| Since Inception P.A. | 9.1% | 5.5% |
^Benchmark: S&P ASX Small Industrials Index. Past performance is not a reliable indicator of future performance.
Inception date: 30/06/2015.
Emerging Companies (Retail) Fund Performance
As at 30 September 2026*
| Fund | Benchmark^ | |
|---|---|---|
| 3 Months | -1.7% | -4.0% |
| 6 Months | -4.5% | 4.1% |
| 1 Year | -25.9% | -14.4% |
| 3 Years P.A. | 0.4% | 6.0% |
| 5 Years P.A. | -4.8% | -1.3% |
| 10 Years P.A. | 6.9% | 4.1% |
| Since Inception P.A. | 8.4% | 5.5% |
^Benchmark: S&P ASX Small Industrials Index. Past performance is not a reliable indicator of future performance.
Inception date: 30/06/2015.
Contributors and detractors
Top 3 contributors to Fund return
+43.3%
Graincorp Limited Class A (GNC)
+22.4%
Pepper Money Ltd (PPM)
+50.2%
Nuix Ltd. (NXL)
Top 3 detractors from Fund return
-33.1%
SiteMinder Limited (SDR)
-35.0%
PEXA Group Limited (PXA)
-43.3%
Somnomed Limited (SOM)Contributors
-
Pepper Money (PPM) outperformed over the quarter despite investors remaining cautious on the outlook for credit growth and quality across the lending sector, following the Budget changes and successive interest rate hikes. We believe the market is underappreciating the earnings accretion from the recently acquired RAMS and HSBC mortgage portfolios, which strengthen Pepper's scale and earnings base in loan servicing. We continue to see value in the business, with these acquisitions and franchise not fully reflected in the current share price..
-
Nuix (NXL) was a strong contributor during the quarter following its announced FY26 result, which demonstrated continued progress across the business. The company delivered double-digit annual contract revenue growth, strong cash EBITDA generation and FY27 guidance ahead of market expectations. Growth was supported by ongoing adoption of the Nuix Neo platform, with customer migrations contributing to higher contract values and an improving revenue mix. Management also continues to invest in AI capabilities and platform development, supporting the company's long-term positioning. We remain positive on Nuix's role in investigative analytics and data governance, with further Neo adoption and pipeline conversion expected to underpin growth over time.
-
Graincorp (GNC) performed strongly over the quarter on an improved FY27 earnings outlook as ABARES increased its East Coast winter crop forecasts by 12% to 26.6mt, well above the 10-year average. Disruption to Black Sea grain supply also pushed global wheat prices sharply higher, which should improve export margins. Graincorp stands to benefit if it can increase volumes through its network when export margins are elevated. Some of the share price gains were given back late in September, when a trading update flagged a six-month delay and about $30m extra cost for its system upgrade, although FY26 guidance was reaffirmed. Looking forward, a normalising margin environment for both the agribusiness and the nutrition and energy business will support the forecast earnings outlook.
Detractors
-
Somnomed (SOM) underperformed during the quarter following a softer second half result, driven by reimbursement and referral pathway changes in Europe that slowed patient access and weighed on growth. While this created near-term pressure, we remain positive on the outlook given the attractive long-term growth opportunity in oral appliance therapy, improving profitability and strong North American momentum.
-
PEXA (PXA) underperformed over the quarter, with the share price coming under pressure as uncertainty around the future pricing framework for the Australian exchange business weighed on investor sentiment. While the FY27 outlook factors in softer Australian property transfer volumes, investor concern is primarily driven by uncertainty around the outcome of the IPART pricing review and its potential implications for the Australian exchange business. Despite this regulatory overhang, the core exchange platform remains a critical part of the property settlement ecosystem. We continue to see value in the business beyond the current regulatory overhang, with the UK operation providing a source of longer-term growth that we believe is not reflected in the current share price.
-
SiteMinder (SDR) detracted over the quarter, with the share price coming under pressure following its FY26 result as investors reassessed the company's medium-term growth outlook, while concerns around the potential impact of AI developments on the travel technology sector also weighed on sentiment. The result included a reduction in annual recurring revenue growth expectations from the previous 30% target to growth in the 20s for FY27. Despite this, underlying operating metrics remained sound, including stable churn and strong customer economics. We continue to see value in the business beyond the current uncertainty, with ongoing adoption of Smart Platform products expected to support future growth over time.
Urbanise.com Limited is one example of a company that brings its own growth drivers to a niche market against established players where we believe the opportunity for market share gains is substantial.
Portfolio changes
Additions to the Fund
- Monvia Limited (MNV) – Monvia is a life insurance software company which we added though participation in its IPO and has attractive growth opportunities in ANZ and international markets.
- Netwealth Group Ltd. (NWL) – We added a position in Netwealth, on the back of recent share price weakness. With the stock trading at an historical low multiple, the current price underappreciates the company's strong market-share growth, scalable platform economics and long-term earnings potential.
- Sims Ltd. (SGM) – We added Sims following share price weakness, viewing the valuation as an attractive entry point into a global recycling business with growing exposure to higher-value e-waste and data-centre recycling opportunities.
- Smartgroup Corporation Ltd (SIQ) – Smart Group has achieved good market share gains in salary packaging services and novated leasing and a recent pull back in the share price, post result provided a good buying opportunity.
Reductions from the Fund
- Arena REIT (ARF) – Arena was sold following the disclosure that one of their major tenants was having financial difficulties. We assessed there might be further risk across the childcare sector and exited the position.
- Bravura Solutions Limited (BVS) – We exited Bravura following a strong share price re-rating, using the strength to redeploy capital into opportunities with more attractive upside.
- Hansen Technologies Limited (HSN) – We sold Hansen after its FY26 result highlighted a weaker growth outlook and increased investment spending, which reduced confidence in the medium-term earnings trajectory.
- Impedimed Limited (IPD) – While we continue to see long-term potential in ImpediMed, we divested the position to focus on other opportunities with nearer-term catalysts and value realisation.
- IPH Ltd. (IPH) – We exited our holding in IPH during the quarter, recognising management's turnaround strategy but acknowledging that the pathway to improved performance is likely to be gradual.
- Perpetual Limited (PPT) – We exited Perpetual around takeover interest resurfacing in the group. FUM flows trends remain subdued and the lift in the share price provided an attractive exit price.
- Rubicon Water Limited (RWL) – We exited Rubicon Water as ongoing delays to US irrigation funding continued to defer contract conversion, increasing earnings and balance sheet risk and reducing confidence in the investment timeline.
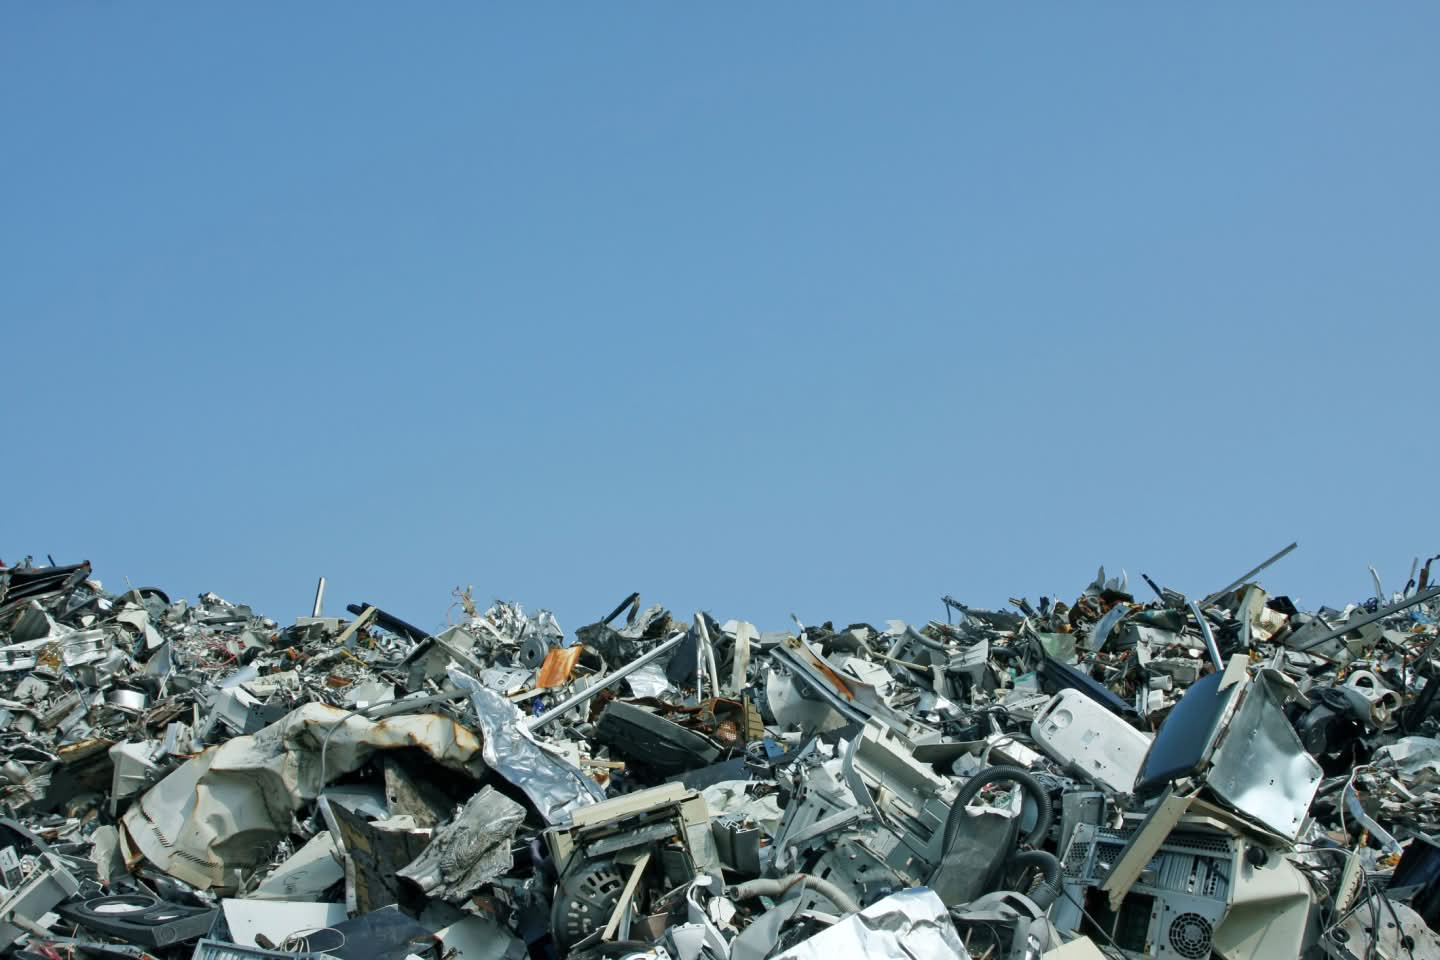
We added Sims to the portfolio during the quarter – one of the world's largest metal recyclers. Sims is a strong example of how the circular economy can cut emissions at industrial scale. The fund re-entered the company at an attractive valuation after its post-result sell-off.
Sector allocation
Sector overweights
Financials, Health Care, Information Technology, Utilities
Sector underweights
Communication Services, Consumer Discretionary, Consumer Staples, Industrials, Materials, Real Estate
Encouragingly, private equity and industry players are seeing long-term value in some of our companies.
Interests in Australian Ethical Managed Funds are issued by Australian Ethical Investment Ltd (ABN 47 003 188 930, AFSL 229949) the Responsible Entity of the Australian Ethical Managed Funds.
The information is of a general nature and is not intended to provide you with financial advice or take into account your personal objectives, financial situation or needs. Before acting on the information, consider its appropriateness to your circumstances and read the Financial Services Guide, relevant product disclosure statement (PDS) and Target Market Determination (TMD) available on our website. You may wish to seek financial advice from a licensed financial adviser before making an investment decision. Past performance is not a reliable indicator of future performance.
Investing ethically and sustainably means that the investment universe will generally be more limited than non-ethical, non-sustainable portfolios in similar asset classes. This means that the portfolio(s) may not have exposure to specific assets which over or underperform over the investment cycle, and so the returns and volatility of the portfolio(s) may be higher or lower than non-ethical, non-sustainable portfolios over all investment time frames.
Our investment restrictions include thresholds and other tolerances that vary depending on the investment. We apply both qualitative and quantitative analysis when making investment decisions and may invest where we believe the positive aspects outweigh the negative. From time to time, we may use derivatives that provide temporary exposure to a broad market index, such as the S&P/ASX 200. This does not involve direct investment in, or ownership of, the underlying companies. For more information, please read our Ethical Guide.
*Total returns are calculated using the sell (exit) price, net of management fees and gross of tax as if distributions of income have been reinvested at the actual distribution reinvestment price. The actual returns received by an investor will depend on the timing, buy and exit prices of individual transactions. Return of capital and the performance of your investment in the fund are not guaranteed. Past performance is not a reliable indicator of future performance. Figures showing a period of less than one year have not been adjusted to show an annual total return. Figures for periods of greater than one year are on a per annum compound basis. The current benchmark may not have been the benchmark over all periods shown in the above chart and tables. The calculation of the benchmark performance links the performance of previous benchmarks and the current benchmark over the relevant time periods.
This commentary may contain material provided by third parties derived from sources believed to be accurate at its issue date. While such material is published with necessary permission, Australian Ethical accepts no responsibility for the accuracy or completeness of, nor does it endorse any such third party material. To the maximum extent permitted by law, we intend by this notice to exclude liability for this third-party material.
The information contained in this document is believed to be accurate at the time of compilation.